India’s borrowing system is changing as more young professionals start using formal credit. For first-time borrowers, applying for a personal loan can feel unfamiliar, with questions around eligibility, documentation, credit history, interest rates, and repayment. Digital lending has made parts of this journey more convenient by letting applicants submit information and documents online. However, digital convenience does not mean automatic approval. Lenders still assess eligibility, repayment capacity, credit-related factors, and other applicable criteria before making a lending decision.
Who Are New-to-Credit Borrowers?
New-to-credit borrowers are individuals with limited or no established borrowing history. This may include young professionals entering formal employment, first-time borrowers, or individuals who have previously relied primarily on savings.
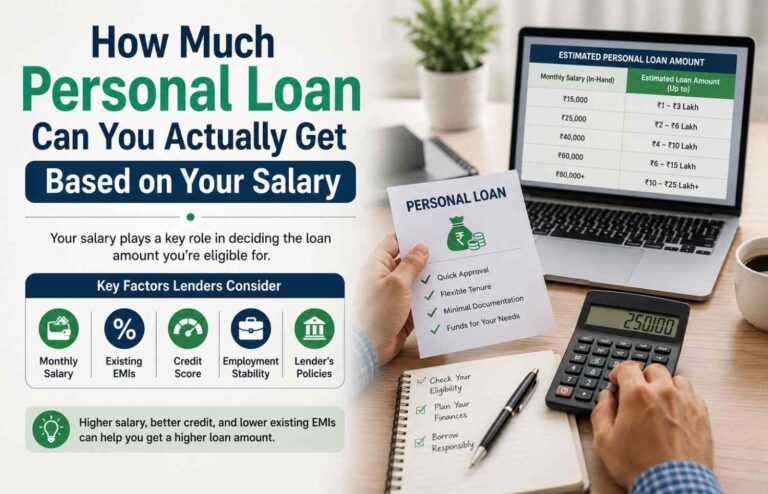
Limited credit history does not automatically determine whether a lender will approve or decline a loan. Lenders may consider several factors, including income, employment, existing financial obligations, repayment capacity, and credit-related information. Understanding these requirements before applying can help first-time borrowers approach the process with greater clarity.
How an Easy Loan App Can Simplify the Process
An easy loan app can bring several stages of the application process into one digital platform. Depending on the lender and product, applicants may be able to provide personal details, select loan requirements, upload documents, and track their application digitally.
This can be particularly useful for first-time borrowers who may be unfamiliar with the lending process. Tata Capital offers a digital loan journey that allows applicants to explore loan options, submit required information, and manage loan-related details online. Its digital platform also offers features such as document submission, application tracking, and support for loan-related queries.
However, applicants should remember that the final decision depends on the lender’s eligibility assessment, verification process, and applicable lending policies.
What First-Time Borrowers Should Know Before Applying
For new-to-credit borrowers, understanding the steps involved in a personal loan application can make the process easier to navigate. From checking eligibility and preparing documents to reviewing repayment terms, each step can help applicants make a more informed borrowing decision.
1. Check Your Eligibility Before Applying
Before applying, review the lender’s eligibility requirements. These may include:
- Age
- Monthly income
- Employment status and work experience
- Credit-related factors
- Existing financial commitments
- Overall repayment capacity
For first-time borrowers, checking eligibility can help you avoid applying for a loan that may not align with your financial profile. Requirements may also vary by loan product and applicant profile, so review the current criteria before submitting an application.
2. Keep Your Documents Ready
Incomplete or unclear documentation can lead to additional verification requirements. Depending on the applicant’s profile, personal loan documentation may include identity proof, address proof, PAN, income-related documents, bank statements, and employment or business-related information.
Tata Capital allows applicants to submit required documents digitally as part of its online loan process. Keeping documents updated and readily available can simplify the application process.
3. Apply for an Amount You Can Comfortably Repay
Loan eligibility and affordability are not necessarily the same. Even if an applicant qualifies for a certain amount, it is important to consider whether the resulting EMI fits comfortably within their budget.
Before you get personal loan financing, consider:
- Monthly income
- Existing EMIs or debt obligations
- Regular household expenses
- Savings and emergency funds
- Upcoming financial commitments
Borrowing only what is genuinely required can help keep repayment obligations manageable.
4. Calculate the EMI Before Accepting the Offer
The EMI depends on factors such as the loan amount, applicable interest rate, and repayment tenure. An EMI calculator can help borrowers understand how different loan amounts and tenures may affect their monthly obligations.
For instance, a longer tenure may reduce the monthly EMI but can increase the overall interest payable over the loan period. A shorter tenure may increase the monthly EMI while potentially reducing the total interest cost.
For new-to-credit borrowers, understanding this trade-off before accepting a loan offer is important.
5. Review the Interest Rate and Applicable Charges
The cost of borrowing involves more than the interest rate alone. Before accepting a personal loan offer, review the applicable terms and charges, which may include:
- Interest rate
- Processing fees
- Loan tenure
- EMI amount
- Penal charges, where applicable
- Prepayment or foreclosure terms
- Other applicable fees or charges
The applicable interest rate and charges can vary based on the applicant’s profile, loan terms, and the lender’s assessment. Therefore, borrowers should carefully review the specific loan offer and relevant terms before proceeding.
Final Thoughts
For India’s new-to-credit generation, a first personal loan does not have to be unnecessarily complicated. Digital platforms can make it easier to understand eligibility requirements, submit documents, and track an application from one place. An easy loan app can simplify the application journey, while an instant loan app can support faster digital processing, subject to verification and eligibility. The key is to borrow responsibly, review the full loan terms, and choose an amount that fits your repayment capacity.
About the Author